Loans Laurelwood households examine online run under Ontario's Payday Loans Act, 2008, in west Waterloo off Columbia Street West beside the Laurel Creek Conservation Area. This page covers single large incomes carrying large mortgages, tech contract endings, university payroll and the $14 per $100 cap.
Quiet money pressure on newer streets
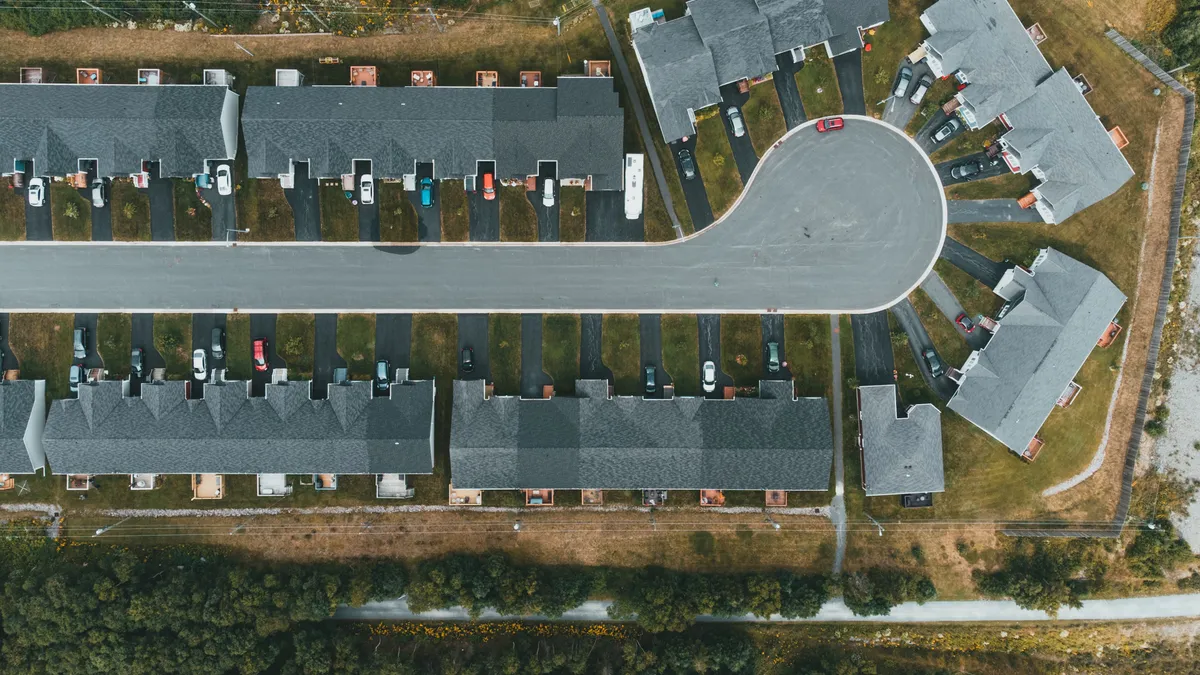
Money pressure in Laurelwood is quieter than elsewhere in the region but real: the 2000s built detached streets skew to university staff, tech workers and dual professional incomes, and the risky shape is a single large income carrying a large mortgage.
When a tech contract ends, that structure can open a gap that lasts for months, and the loans Laurelwood residents look into at that point are rarely the payday kind.
University payroll, tech offices by the R+T Park station, and the drive
Work is the universities, the tech offices near the Research and Technology ION station, and clinics and schools across Waterloo, with most households driving and GRT buses running Columbia and Erbsville Road. The library and YMCA complex on Fischer-Hallman is the neighbourhood hub.
University and school payroll is biweekly and predictable, exactly the deposit shape Ontario's payday rules assume: a loan capped at 50% of the period's net pay, repaid in one debit on the next pay date.
Match the loan to the horizon, not the shock
The horizon decides the product: a dated bill inside a pay cycle is payday shaped, a months long income gap is not. A $800 appliance failure against a university cheque next Friday costs $112 at the legal cap, with $912 debited Friday, and the mortgage payment stays untouched.
A contract ending with no successor runs on a different clock, and stretching payday loans across it is the one use Ontario's structure is designed to resist, through the rollover ban and the single repayment date.
The Laurelwood cases side by side
Side by side, the loans Laurelwood owners actually compare split cleanly between the one cheque fix and the monthly plan.
| Household | The event | What tends to fit |
|---|---|---|
| University staff on biweekly payroll | An $800 appliance days before payday | A payday loan repaid on the biweekly date |
| Tech worker, contract ending in March | Months until the next salary | A personal or installment loan, repaid monthly |
| Dual professional household | A renovation stage past $1500 | $500 to $10000 over 3 to 60 months |
| Commuting parent, one car in the shop | A rental car week before payday | A small payday loan, repaid once |
The personal loans Kitchener page and the installment loans Kitchener page cover the monthly route at 18% to 35% APR; the Kitchener loan FAQ handles the judgment calls between them.
The same Act beside the conservation area
Beside Laurel Creek the law reads as it does everywhere in Ontario: payday lenders hold a licence per business and per location under the Payday Loans Act, 2008, online lenders included, with the fee capped at $14 per $100 and every figure disclosed in writing first. Consumer Protection Ontario takes complaints.
Borrowers are 18 or older, can cancel within two business days at no cost, cannot roll over a loan or hold two at once, and are owed an extended payment plan offer on a third loan inside 63 days. The federal payday loan guide and our how it works page cover the details; the Loans Kitchener homepage is clear that we match borrowers to licensed lenders for free and never lend.
From the areas we serve hub: the University District and its co-op calendar sit east down Columbia, Uptown Waterloo holds the head offices further along King, and Highland West is south across the city line at the Boardwalk.
Apply online from LaurelwoodLoans Laurelwood FAQ
My spouse earns well but I am between tech contracts. Can the household income back my loan?
No. A payday loan reads one applicant's own payroll deposits and chequing account. The earning spouse could apply on their own income, but a months long gap is still better served monthly.
Is it sensible to use a payday loan to protect a mortgage payment once?
Once, with a scheduled cheque behind it, the math works: the debit and fee land on the next payday and the mortgage never misses. If protecting the mortgage would need a second loan, stop at one and rework the plan.
I work at the university and get paid biweekly. What does a $600 loan actually cost?
$84, the capped 14% fee, so $684 is debited on your next pay date. No licensed Ontario lender can charge more for a payday loan, however it is marketed.
We would rather not touch the line of credit. Is a payday loan cheaper?
Almost never. A 14% fee over two weeks works out to about 365% annualized, far above any bank line. A payday loan buys speed on a small dated gap, not cheap money.
Loan options in Kitchener
One page per product: who qualifies, how fast it funds and what to check before you sign.